Good questions deserve clear answers.
Explore the details behind life insurance, Medicare, IUL and annuity decisions. These answers provide a starting point; your policy, state and personal circumstances still matter.
Find your question
Search all 60 answers or choose a topic. Questions appear five at a time.
60 questions
No questions match. Try another phrase, choose another topic or reset the filters.
Who is Angie Brannon?
Angie Brannon, also known as Angie Brannon, is the insurance professional behind Brannon Wealth in Milroy, Pennsylvania. Her work focuses on life insurance, Medicare, indexed universal life, fixed indexed annuities, Roth conversion strategies, retirement planning, mortgage protection, existing-policy reviews and debt management, and she is licensed in all 50 states. Her National Producer Number is 17254013. She brings a background in helping people understand Medicare and a personal commitment to making insurance conversations easier to follow.
What can I talk with Brannon Wealth about?
Start with the question you actually have: protecting your family, understanding Medicare options, reviewing an existing life policy, exploring IUL or a fixed indexed annuity, weighing Roth conversion strategies alongside your tax professional, planning retirement income, covering a mortgage, or getting debt questions into the open. Angie can help you identify what needs a closer look. A conversation is not a promise that any particular policy is appropriate or available; that depends on your circumstances, state, underwriting and the insurer’s terms.
Where is Angie based, and which states is she licensed in?
Angie is based in Milroy, Pennsylvania, and she is licensed in all 50 states, so a conversation can start wherever you live. Her National Producer Number is 17254013, and the licensing section links the official lookup so you can check her record in your own state. An active license alone does not make every insurance product available everywhere; insurer appointments and product requirements also apply.
Who is Angie’s approach especially relevant to?
Angie’s approach is especially relevant to working families, people in trades and physical occupations, independent professionals and households with income that changes during the year. Those situations can raise practical questions about affordable premiums and keeping coverage in force. You do not need to fit a particular job title to ask for a review; start with the people and responsibilities you want to protect.
How do I contact Angie Brannon?
Call (717) 320-4022, email angiebrannon42@gmail.com or use the Brannon Wealth contact form. Include your state and the topic you want to discuss. You can begin with a simple question rather than a detailed application. Do not send Social Security numbers, account credentials or medical records through an ordinary website message or email; ask about an appropriate secure process if documents are needed.
What should I bring to a first insurance conversation?
Bring your main question, a rough household budget, the people who depend on your income and any existing policy summaries you want to understand. For an annuity discussion, a recent contract statement can help identify charges, guarantees and access rules. You do not need every answer in advance. Share sensitive documents only through an appropriate process arranged with Angie.
Can Angie review a policy I already own?
Yes. Existing-policy questions are a natural fit for Angie’s review approach. Useful starting points include your coverage amount, premium, beneficiaries, current values and any notices you have received. A review should explain what you have before considering changes. Do not cancel or surrender existing coverage merely to begin a conversation; a replacement can involve new costs, underwriting and benefit differences.
What does independent insurance professional mean here?
Angie describes an independent approach, and state records show appointments with multiple insurers. That can allow consideration of more than one company’s options where she is authorized and appointed. It does not mean access to every insurer or every product. Ask which companies are being considered and why a particular option fits your needs.
What experience does Angie bring to these conversations?
In a 2023 interview, Angie described assisting people with Medicare through a local Area Agency on Aging and later continuing volunteer help during open enrollment. She clarified that the agency work was not as an insurance agent. Florida records show a licensing history dating to 2014; her current Pennsylvania license was originally issued in 2023. These dates should not be read as continuous full-time sales experience.
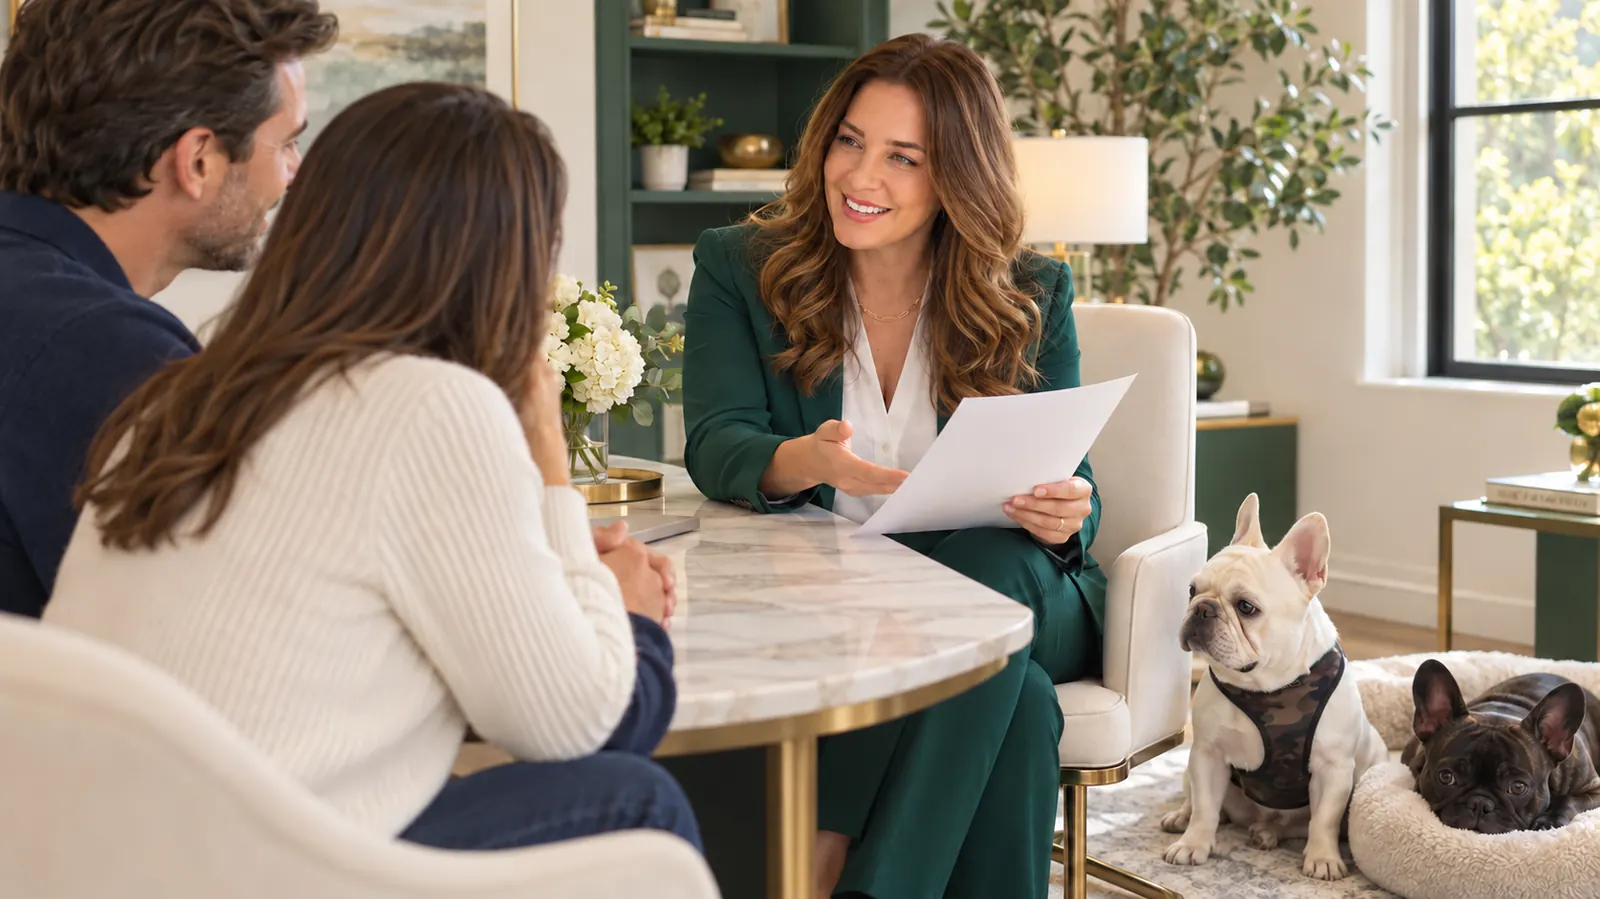
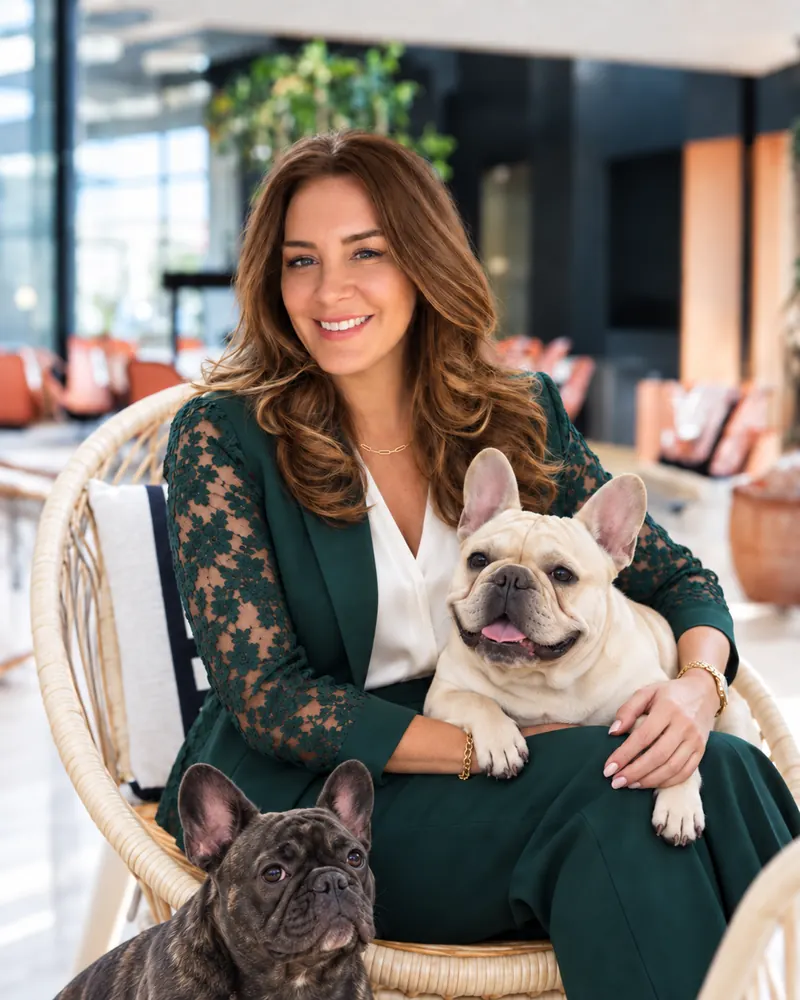
Why are French bulldogs part of the Brannon Wealth website?
Angie has six French bulldogs, and they are part of the personality behind Brannon Wealth. The photos give you a glimpse of the person you will be speaking with. The insurance conversation itself stays focused on your household, your questions and the terms of any coverage you are considering.
How much life insurance should I consider?
Start with what would need to be paid if you died: ongoing household costs, debts, care responsibilities and future goals. Then consider savings and existing coverage that could help. Income alone is not the whole picture, especially when someone provides unpaid caregiving. Angie can discuss your priorities, but the right amount should come from your situation rather than a universal salary multiplier.
How do term life and permanent life insurance differ?
Term insurance provides coverage for a stated period if required premiums are paid. Permanent insurance is designed for longer-term coverage and may build cash value, but its costs and funding requirements differ by policy. Comparing them means looking at how long protection is needed, what you can sustain and the actual guarantees. This is an educational comparison, not a statement that every policy type is available through Angie.
Is the life insurance from my job enough?
It may provide useful protection, but check the benefit amount and what happens if your job ends or your hours change. Employer coverage may not match all of your household’s needs, and portability or conversion provisions can have conditions. A review can compare your work benefit with your responsibilities without assuming you need to replace it or buy more.
Can someone with seasonal or uneven income plan for life insurance?
Yes, but premium affordability deserves particular attention. Consider a realistic budget through slower months rather than only your best earnings period. Angie’s work specifically considers households with uneven income. If a policy allows flexible payments, ask what happens to charges, values and coverage when payments are reduced; flexibility does not eliminate the need to fund the policy.
Does working in a trade or physical job affect insurance?
Insurers may consider occupation and duties along with health, age and other underwriting information. Describe the work accurately, including any hazardous activities. Angie’s site specifically welcomes conversations with people in physical jobs, but that does not guarantee approval or a particular price. Compare the actual policy and underwriting outcome rather than assuming every trade is treated the same way.
Can a stay-at-home parent need life insurance?
Potentially. Childcare, transportation, household management and other unpaid work can carry a significant replacement cost. The discussion should consider what the surviving household would need and for how long, not just earned income. Budget, existing resources and the insurer’s eligibility rules matter when choosing an amount and type of protection.
Will I need a medical exam for life insurance?
That depends on the insurer, policy, coverage amount and your underwriting information. Some applications may qualify without an exam, but no-exam underwriting does not mean automatic approval, no health questions or the same price for everyone. Ask Angie whether a no-exam option fits your situation; this website does not promise one is available to every applicant.
How are whole life and IUL different?
Both are forms of permanent life insurance, but their funding, guarantees and cash-value mechanics differ. Whole life commonly uses scheduled premiums and contractual cash-value guarantees; IUL uses index-linked crediting subject to policy terms and ongoing deductions. Compare actual illustrations and guaranteed values rather than labels. This explanation is educational; ask Angie which products she currently offers in your state.
When should I review my beneficiaries?
Review beneficiary choices after significant changes such as a birth, death, marriage, divorce or a change in caregiving responsibilities. Confirm that the insurer has your intended designation on file and that contingent beneficiaries are considered. Naming minors, a trust or an estate can create additional questions, so involve an appropriate legal professional when necessary.
Should I replace an older life insurance policy?
Not automatically. Compare the existing benefits, values, premiums and guarantees with any proposed coverage, including new underwriting and surrender costs. A new policy may also start new contestability or suicide-exclusion periods under its terms. Keep existing protection in place while you understand the comparison and any replacement requirements; a review is not a commitment to replace.
What is indexed universal life insurance?
Indexed universal life, or IUL, is permanent life insurance with cash-value crediting that can be linked to an external index under the contract’s formula. Its primary purpose remains a death benefit. Policy charges, funding requirements and index-crediting limits affect results. IUL is one of the topics Angie discusses, and it deserves a detailed, questions-first review.
Is an IUL policy invested directly in the stock market?
No. In an index-linked crediting option, the insurer uses an index measurement to calculate interest under the policy’s rules; you do not own the index’s stocks through that option. The policy can have limits on credited interest and ongoing insurance charges. It should not be described as getting the full stock market return without investment risk.
Does an IUL crediting floor mean my cash value cannot fall?
No. A floor applies to the specified index-crediting calculation, not to every change in policy value. Insurance costs, administrative charges, withdrawals or loans can reduce values even when the index-crediting rate is not negative. Ask to see how the policy performs after deductions and what happens under less favorable crediting assumptions.
What are caps and participation rates in an IUL policy?
These are examples of limits or formulas used to calculate credited interest. A cap may limit the rate credited for a period; a participation rate determines how much of the measured index change is used. Some options use other adjustments. Ask which terms can change, what their contractual minimums are and how those changes could affect an illustration.
Are the values in an IUL illustration guaranteed?
Not all of them. An illustration may show guaranteed and non-guaranteed elements, and projected values can rely on assumptions that will not match future results. Ask which columns are guarantees, which assumptions can change and how much premium may be needed if results are lower. A favorable projection is not a promise of future cash value or income.
Can I reduce or skip an IUL premium whenever I want?
A policy may offer premium flexibility, but coverage still needs sufficient funding under its terms. Charges generally continue, and lower funding can affect cash value, guarantees and lapse risk. Before changing payments, request an updated explanation of how the change could affect the policy. Do not equate a flexible payment feature with free or automatically permanent coverage.
How do policy loans differ from withdrawals?
A withdrawal removes value from a policy under its terms. A policy loan is borrowing secured by policy value and generally involves interest. Either can affect what remains available and the death benefit; a loan can also increase lapse risk. Ask for a policy-specific illustration before using either feature and discuss potential tax consequences with a qualified tax professional.
Is money taken from a life policy always tax-free?
No. Tax treatment depends on the policy, the transaction and your circumstances, including whether a contract is a modified endowment contract and whether it remains in force. Loans, withdrawals or a later lapse can have consequences. Treat any promise of universally tax-free retirement income with caution, and coordinate policy decisions with a qualified tax professional.
Should I replace my 401(k) with IUL?
There is no universal reason to do that. Employer retirement plans and life insurance serve different purposes and have different costs, rules and potential benefits. Employer matching contributions, taxes, liquidity and your actual need for a death benefit all matter. Review the complete household picture with the appropriately qualified professionals before redirecting retirement savings.
How often should an IUL policy be reviewed?
Review it regularly and when income, goals, beneficiaries or planned funding change. Ask for an in-force illustration and review premium history, deductions, loans and current assumptions. An annual check can provide a useful routine, but a warning notice or planned withdrawal should prompt attention sooner. Do not wait for a problem to understand how the policy is performing.
What are living benefits in life insurance?
The term can refer to provisions allowing certain benefits while the insured is alive, such as an accelerated death benefit after a qualifying illness. Coverage definitions and availability vary by policy and rider. Angie can walk through living-benefit questions, but the phrase alone does not tell you which conditions qualify or what amount could be paid.
Are living benefits the same thing as cash value?
No. A qualifying accelerated death benefit is tied to specified policy conditions, often involving illness. Cash value is a separate policy feature that may be accessible through loans, withdrawals or surrender under the contract. One does not guarantee the other. Ask which feature a proposed policy includes and what costs, eligibility conditions and tradeoffs apply.
Which illnesses qualify for a living-benefit payment?
Only the conditions and definitions written into the particular policy or rider determine eligibility. Labels such as terminal, chronic or critical illness can have different triggers and requirements. Ask for the actual rider language, waiting periods, limits and any required certifications. A diagnosis by itself should not be assumed to qualify under every contract.
Can using living benefits reduce the death benefit?
Yes. Accelerating part of a death benefit generally reduces what remains payable at death, and the amount received may reflect charges or a discount under the contract. Ask for an example showing both the payment and the remaining benefit. Consider the effect on the people you originally intended to protect before making a claim decision.
Do life-insurance living benefits replace health or disability insurance?
No. They should not be described as substitutes for ordinary health coverage, disability-income insurance or every long-term-care need. Each product has a different purpose and eligibility rules. A living-benefit provision may help in a qualifying situation, but it is not a promise to cover all medical costs or replace a paycheck whenever you cannot work.
What is an annuity?
An annuity is a contract with an insurance company. Depending on the contract, money may accumulate for a period or be used to provide income. Understanding an annuity requires looking at its purpose, access rules, charges and guarantees. Angie’s public posts discuss annuities; a personal conversation should establish whether a particular contract fits your situation.
How is an annuity different from life insurance?
Life insurance primarily addresses a death benefit for beneficiaries. An annuity is commonly considered for accumulation or income during the owner’s or annuitant’s lifetime, depending on the contract. Both are insurance contracts, but they are not interchangeable. Start by identifying whether your main concern is protecting others after death or managing money and income during retirement.
Can an annuity provide income for life?
Some contracts or income options can provide payments for a specified person’s lifetime. That depends on the actual payout choice or rider, eligibility requirements and contract conditions. A guaranteed withdrawal benefit is not the same as freely accessible cash value. Insurer guarantees depend on the issuing company’s claims-paying ability; not every annuity automatically includes lifetime income.
What is the difference between a fixed and a fixed indexed annuity?
A traditional fixed annuity credits interest according to its contract’s rate provisions. A fixed indexed annuity uses a formula linked to an index for some crediting options, usually with limits. Both require a close look at guarantees and access terms. This is an educational comparison; ask Angie which specific categories and contracts are currently available through her in your state.
Can I withdraw money from an annuity whenever I need it?
Contract access rules vary. An annuity may permit some withdrawals without a surrender charge while charging for larger or earlier withdrawals. Other adjustments and tax consequences may also apply. Keep money needed for near-term expenses and emergencies in the discussion before committing funds, and ask for a written explanation of the specific withdrawal rules.
What is a surrender charge?
A surrender charge is a contract charge that may apply when you take out more than the permitted amount during a stated period. The schedule and exceptions vary. Ask when the charge period ends, whether a new contract would restart it and how other adjustments might affect the amount available. A review should make those tradeoffs clear before a purchase or replacement.
Do annuities have fees or other costs?
They can. Costs may appear as explicit rider or contract charges, surrender charges, or limits built into the crediting design. A product described as having no annual fee can still have important economic tradeoffs. Ask what you pay directly, what limits potential credits and what it costs to access or move your money.
Will annuity income automatically keep up with inflation?
Not necessarily. A fixed payment can lose purchasing power as prices rise. Some contracts or payout choices offer ways payments may change, but those features can involve costs or a different starting benefit. Consider essential expenses, other income sources and the actual contract rather than assuming an income guarantee also guarantees purchasing power.
Can Angie help me understand an annuity I already own?
An existing annuity is a useful starting point for an annuity-options conversation. Bring the contract and a recent statement so its payout provisions, surrender schedule, riders and beneficiaries can be identified. Do not assume a newer contract is better. A proposed change should account for benefits lost, new costs and any relevant tax or replacement implications.
Are annuity guarantees the same as a bank deposit guarantee?
No. An annuity is an insurance contract, not a bank deposit, and its contractual guarantees depend on the issuing insurer’s claims-paying ability. Do not treat an insurer guarantee as a federal deposit guarantee or assume the principal can always be withdrawn without charges. Ask exactly what is guaranteed, by whom and under which conditions.
What is Angie’s Pennsylvania insurance license number?
Her Pennsylvania resident license is 1114244. The official record checked September 16, 2026 showed it active, with an expiration of January 31, 2028. Her National Producer Number is 17254013, and that number identifies her on any state’s official lookup, including yours.
How do I verify Angie’s license in my state?
Use an official state lookup: select your state, choose the individual search, and enter Angela Sue Brannon, her legal licensing name, or NPN 17254013. Records checked on September 16, 2026 included Florida W190743, Nevada 3958651 and Texas 2981878. Check the official lookup for current status rather than relying on an undated directory listing.
Can I contact Angie if I live in another state?
Yes. Angie is licensed in all 50 states, so reach out from anywhere and tell her which state you are in at the start. Before any product-specific recommendation, application or sale, the insurer appointments and product rules for your state still apply, and what is available can differ from one state to the next.
Does Angie currently sell Medicare insurance?
Yes. Medicare is one of Angie’s current services. You can contact her about understanding your options and reviewing questions about existing coverage. Ask which plan types and insurers she represents in your area; availability depends on your location and the applicable requirements. Her earlier Medicare-assistance work is part of her background, separate from her current insurance sales role.
Does Brannon Wealth provide investment, legal or tax advice?
The services described here are insurance conversations and education. This site does not establish securities registrations, investment-adviser status or legal and tax qualifications for Angie. Insurance decisions can affect a broader financial plan, so involve appropriately qualified professionals for those areas. An insurance license category containing “variable annuity” should not be treated as proof of separate securities authorization.
What should I bring to a Medicare conversation?
Prepare your ZIP code, current coverage, preferred doctors and hospitals, prescription list and preferred pharmacies. These details make a comparison more relevant than looking at a premium alone. Do not put Medicare numbers, medical records or Social Security numbers in the website’s ordinary contact form; ask Angie how to provide any sensitive information securely.
What is the difference between Original Medicare and Medicare Advantage?
Original Medicare generally means Part A and Part B through the federal program. Medicare Advantage is a private-plan way to receive those benefits under Medicare rules, often with drug coverage included. Network and cost rules differ. This is a general explanation, not a statement that Angie represents every plan; ask about the options she can offer in your location.
Is Medicare Supplement insurance the same as Medicare Advantage?
No. Medicare Supplement insurance, also called Medigap, works with Original Medicare to help pay certain covered out-of-pocket costs. Medicare Advantage is a different way to receive Medicare benefits. They should not be presented as interchangeable products. Ask Angie which categories she currently offers and consult the official Medicare guidance before deciding between coverage paths.
What does Medicare Part D cover?
Part D is Medicare prescription drug coverage. Plans have their own covered-drug lists, pharmacy arrangements and cost rules, so compare your actual medicines rather than assuming all plans cover them alike. Drug coverage may be offered separately or included in a Medicare Advantage plan. Ask which drug-plan options Angie can discuss for your area.
Can I keep my doctor with any Medicare plan?
Do not assume so. Before choosing a plan, verify your physicians and hospitals against that specific plan’s current network or participation rules. A familiar insurer name is not enough because its plans may differ. Include specialists and any regular treatment locations in the review, and confirm information with both the plan and provider when needed.
Why should I review my Medicare coverage each year?
Your prescriptions, providers and care needs can change, and plan details can change too. An annual review is an opportunity to compare the coming year’s coverage with what you actually use. It does not mean you must switch plans. Bring current documents and questions, and use the applicable enrollment rules before making any change.
Can I enroll in or change Medicare coverage at any time?
Enrollment opportunities depend on the type of coverage and your circumstances. Initial, annual and special enrollment rules are not interchangeable, and not every change is available year-round. Tell Angie about upcoming coverage changes, but verify the applicable timing through Medicare before acting. The official Medicare enrollment guide is linked on the Medicare page.
Is the lowest Medicare plan premium always the lowest-cost choice?
No. A premium is only one part of a coverage comparison. Consider deductibles, copayments, coinsurance, drug costs, provider access and the services you expect to use. A plan that looks inexpensive at first glance may have tradeoffs that matter to you. Compare the complete picture for your location and needs rather than choosing on a headline price alone.
What if I am still working or have coverage from an employer?
Speak with your benefits administrator before changing coverage or assuming you can delay Medicare enrollment. Employer or union coverage can interact with Medicare in ways that affect you and dependents, and giving up coverage can have consequences. Bring the details to your conversation with Angie and use official guidance to understand the applicable rules.
Is Brannon Wealth a government Medicare office?
No. Brannon Wealth is an insurance business, not Medicare or a government agency. Angie sells Medicare insurance, subject to the plans and areas she is authorized to serve. You can also use Medicare.gov, call 1-800-MEDICARE or contact your State Health Insurance Assistance Program for official or independent information about coverage choices.
Still have a question?
Ask it directly. Tell Angie your state and what you’re thinking about, and the conversation will start there.